ASIC has uncovered widespread transparency and governance failures among private credit funds, warning that investors remain poorly informed about fees, conflicts, and risks.
The Australian Securities and Investments Commission (ASIC) has identified extensive disclosure and governance shortcomings among Australia’s private credit funds, finding investors are still being denied essential information.
Published on Tuesday (10 November), the regulator’s latest examination uncovered inadequately explained charges, complicated ownership arrangements and financial advice recommending substantial exposure to individual funds.
It said that most poor practices previously brought to the industry’s attention remained unresolved a year later.
ASIC exercised compulsory information-gathering powers to examine 24 retail and wholesale funds overseeing $18 billion between November 2025 and August 2026.
It separately scrutinised 46 instances of personal advice delivered to retail clients by 19 advisers.
Its 58-page report, Private credit funds: Do investors know what they’re getting? (REP 846), follows earlier surveillance that prompted demands for better disclosure, distribution, and conflicts management.
ASIC acknowledged improvements in parts of the market but found that numerous weaknesses remained.
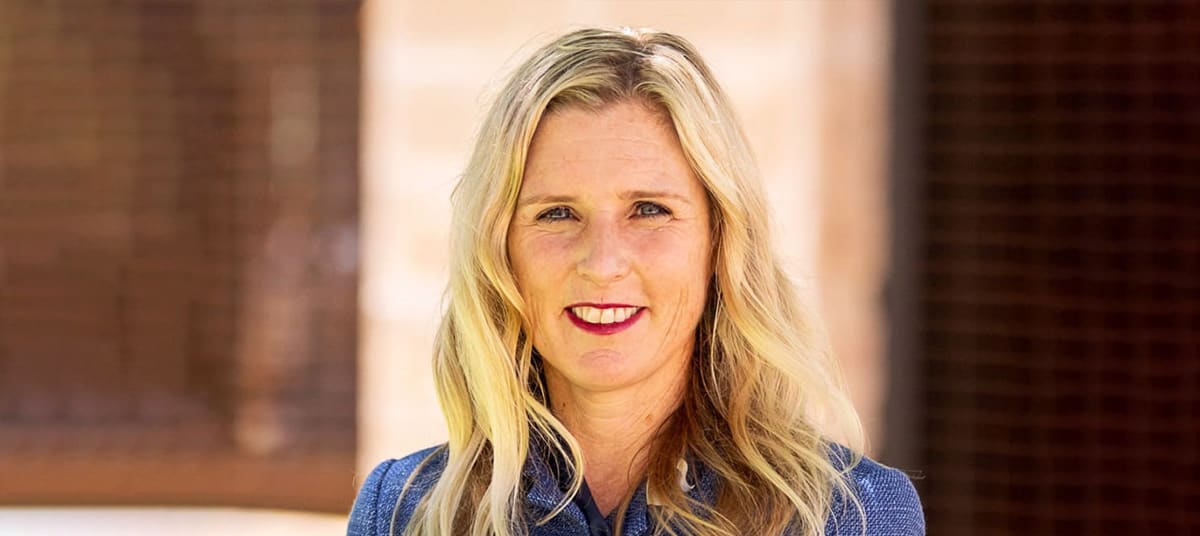
Commissioner Simone Constant said the industry was asking too much of investors who simply wanted to understand how their capital would be deployed.
“Investors should not need a PhD in corporate finance to understand how funds operate,” she said.
Lending income reveals gaps in fee disclosure
A major focus was the difference between the income generated by lending activities and the amounts ultimately reaching investors.
Across the relevant group of 22 funds, ASIC found only two “passed on the full economic benefit of interest and borrower fees onto investors”.
Retail funds retained interest margins reaching 5.6 per cent relative to investor payments, with wholesale funds recording margins as high as 5.9 per cent.
More than half the funds surveyed also retained default interest collected from borrowers rather than distributing it to investors.
The most pronounced example involved a lender connected to a fund keeping borrower fees, interest margin and default interest that investors had not been told about.
Using approximate figures, ASIC calculated that those benefits exceeded four times the fund’s disclosed management costs and added that during the 2025 calendar year, the related party received the equivalent of 38¢ for each $1 distributed to investors.
The issue was not confined to that example, with seven of 10 retail funds and nine of 12 wholesale funds in the analysis retaining establishment or origination fees, and two failing to disclose the practice.
Constant said she was not surprised that borrower charges and fund distributions differed, adding that her concern was whether investors had enough information to decide if the return offered adequately compensated them for putting their capital at risk.
“We are not the returns police. We are not the margin police. However, we are the conduct regulator, and we are calling out that the pricing of risk and the treatment of risk need to be consistent with what’s disclosed to those investors,” she said.
Interconnected entities complicate scrutiny of investor money
The review found disclosure deficiencies across 22 of the 24 funds, alongside arrangements involving associated entities that investors could not always readily understand.
A total of 18 funds channelled investments through several intermediary layers, including special purpose vehicles (SPVs), fund-of-funds arrangements and warehouse vehicles.
ASIC’s concern was that insufficient explanation left investors struggling to trace their money and assess the consequences of related-party decisions.
In one instance, approximately 17 per cent of a fund’s assets were moved within a year to other funds operated by the same management group without adequate disclosure.
ASIC said SPVs played a material role in 10 of the 12 wholesale funds, compared with three of the 12 retail funds and that some funds had used more than 500 vehicles over their operating lives.
Constant said certain groups maintained more SPVs than people employed to manage investors’ money, creating arrangements in which effectively communicating risk became close to impossible.
“Investors should not need forensic skills to understand how a fund operates,” Constant said.
“This is our line in the sand about managing these interests, these relationships, and moving to more transparency, tighter governance, and appropriate conflicts of interest practices to support those structures and the fair treatment of investors.”
Retail disclosures and advice attract particular concern
ASIC found nine of the 12 retail funds had not adequately communicated information investors needed to assess their investments, including the condition of troubled loans.
Two funds reported loan default rates of 18 per cent and 25 per cent but provided little or no explanation to help investors interpret those figures.
The regulator also criticised the target market determinations of 10 retail funds.
ASIC said problems included risk descriptions that were too broad or unclear and allocation recommendations ASIC considered unsuitable.
It added that promotional material raised further concerns about whether investors understood the distinction between private credit investments and money held with a bank.
Some operators incorporated terminology such as “savings account” into advertising or search terms while one promoted access to invested money at any hour, even though that access was not available.
Across three retail funds, ASIC found marketing gave excessive prominence to returns, stability, liquidity, or preservation of capital.
Separately, the advice examination revealed that recommendations were committing large proportions of a client’s money without sufficient evidence that the advice satisfied legal obligations.
Among files recommending private credit allocations above 20 per cent, 88 per cent failed to demonstrate compliance with the best interests duty.
The largest proposed exposure to one fund was 87 per cent of a client’s portfolio.
Another case involved a woman in her late 50s, assessed as having a conservative attitude to risk, who was advised to place half her available money in a single private credit fund.
Repeat findings increase pressure for regulatory action
The findings come as private credit assumes a larger role in financing Australian borrowers, with the industry continuing to attract money from a broader investor base.
Drawing on estimates published in the media, REP 846 placed lending by the sector above $250 billion in 2026, with ASIC noting that increasing participation through direct retail investment and superannuation broadened the potential consequences when funds inadequately explained risks.
ASIC’s surveillance has already generated six interim stop orders and multiple referrals for further enforcement investigation.
Separately, on 9 November, ASIC imposed interim stop orders on two Angas Securities funds over disclosure concerns, including one fund’s exposure to collapsed property developer Bathla Group.
Constant said the responsibility for rectifying shortcomings was now “up to the industry”, making clear that the regulator expected earlier warnings to translate into changes in practice.
“It is disappointing that we see too much repeat of bad behaviour and too much repeat of our concerns,” she said.
Asked about the response to the problems uncovered, she said that ASIC would weigh the potential investor harm alongside the disclosure deficiencies.
“We’re looking at a whole range of regulatory responses that will be appropriate to the potential harm and disclosure,” Constant said.
Addressing poor private credit practices remains a 2026–27 enforcement priority, with several investigations underway.
ASIC said it would consult in early 2027 on revised fund guidance, including a proposal to broaden Regulatory Guide 45 beyond mortgage schemes to cover private credit funds more generally.
It is also pursuing powers to collect information regularly from managed investment schemes, which would give it a more consistent view of the sector.
[Related: ASIC freezes mortgage fund as private credit scrutiny mounts]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.