Brokers dominate Macquarie’s mortgage originations as its expanding loan book closes in on another major milestone.
Macquarie Bank, the Australian banking arm of Macquarie Group, has grown its home loan portfolio to $198.2 billion, with brokers accounting for more than 95 per cent of its mortgage originations.
The bank’s results for the six months to 30 September 2026 showed that its mortgage portfolio increased by 9 per cent from the $181.3 billion comparison balance, bringing it within $1.8 billion of the $200 billion mark.
Its share of the Australian mortgage market reached 7.6 per cent in September, up from 7.1 per cent in March, following a financial year in which its home loan portfolio expanded by 28 per cent.
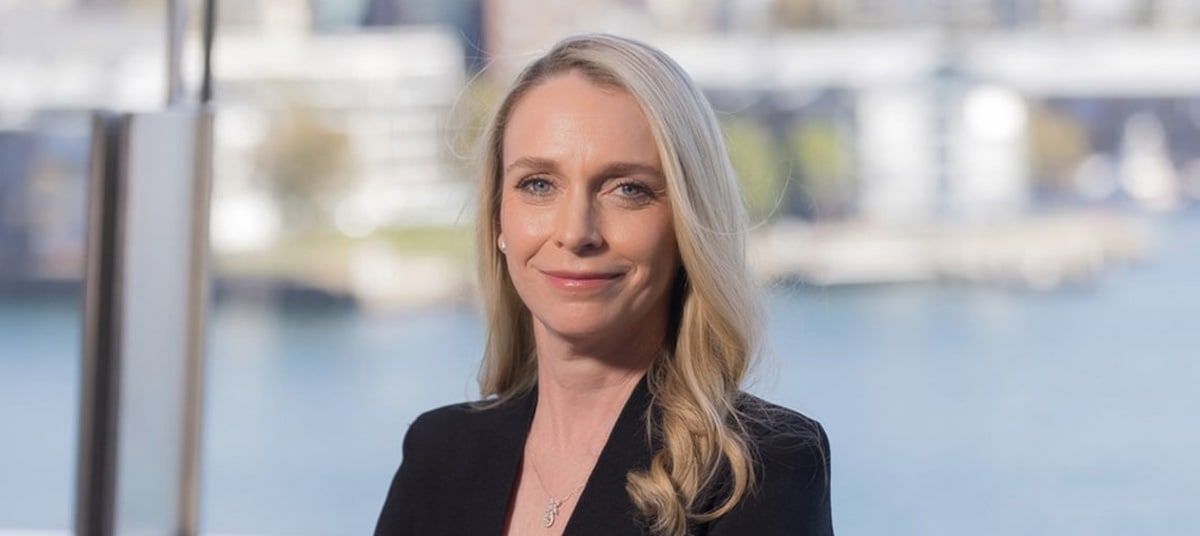
Wendy Brown, Macquarie Bank’s head of home loan and commercial broker sales, attributed the market-share gains to a broader shift in how Australians were choosing their lenders.
“Our growth to 7.6 per cent of the home loan market forms part of a longer-term trend. More Australians are looking beyond their legacy banking relationships and partnering with brokers to find greater value and a better experience from their lender,” she said.
Brown said borrowers were scrutinising their existing arrangements more closely, with brokers playing a central role in discussions about whether to move lenders.
“We’ve seen plenty of change in the market over the past year, with customers taking a much closer look at their finances, reassessing their home loan options and considering whether refinancing could make sense for them,” Brown said.
“Brokers are often at the centre of those conversations, helping customers understand their options and navigate what can be a complex process.”
Investment aims to keep service ahead of growth
Macquarie said demand from borrowers seeking lower loan-to-value ratio (LVR) and owner-occupied lending was supporting its expansion, consistent with its focus on those segments.
Average LVR at origination was 66 per cent in September, while the portfolio’s average dynamic LVR stood at 55 per cent.
Owner-occupied lending represented 63 per cent of the home loan book, and just 4 per cent of borrowers were on fixed-rate terms.
Alongside that lending focus, Macquarie said technology investment was enabling “market-leading” turnaround times.
Brown said maintaining service standards as the business expanded required investment across staffing, processes and digital infrastructure.
“As we grow, it’s really important for us that we don’t compromise on what sets us apart. That’s why we’re focused on the fundamentals,” she said.
“We’re investing to scale our teams and streamlining our processes so we can maintain our market-leading turnaround times. We’ve been growing our locally based credit and BDM teams and also continuing to enhance our digital platforms.”
Further changes are planned, with Brown flagging new tools and policy developments over the coming weeks and months.
“I think the really exciting thing is there is so much more to come. We’ve got some great new tools and policy changes in the pipeline that build on what we’ve already delivered,” Brown said.
“We’ll be rolling these out over the coming weeks and months and we’re confident brokers and their customers are we know brokers and customers are going to love what we’ve been working on.”
While the result reinforces the importance of third-party distribution to Macquarie’s mortgage business, the bank also identified growing direct retail distribution as a medium-term growth opportunity.
That ambition comes as Westpac, the National Australia Bank (NAB), and the Commonwealth Bank of Australia (CBA) continue to prioritise proprietary lending.
Westpac’s full-year results, released earlier this week, showed that the proprietary share of new mortgage originations at the bank had increased to 37.2 per cent in the second half of FY25–26.
Meanwhile, NAB, which also released its full-year results this week, revealed that proprietary channels now accounted for 52.5 per cent of new mortgage flows in 2H26, the highest direct share in its recent history.
Loan growth supports income as competition squeezes margins
Macquarie’s banking division reported net interest and trading income of $1.635 billion, up 12 per cent on the corresponding half.
A 22 per cent increase in the average loan portfolio supported the result, although lower margins partly offset that benefit.
Macquarie attributed the margin pressure to changes in portfolio mix and continuing lending competition.
Macquarie’s mortgage expansion contrasted with slower growth at Westpac and NAB as the banks grapple with a mounting mortgage downturn.
Westpac’s home loan growth eased to 2.7 per cent in the second half from 4.2 per cent in the preceding six months, while NAB’s mortgage portfolio increased by 1.1 per cent over the six months to September and 3.6 per cent over the year, against annual system housing credit growth of around 7 per cent.
NAB’s new lending originations also fell to $39 billion from $47 billion in the corresponding prior-year half, a reduction of approximately 17 per cent.
Macquarie identified global volatility, inflation, rising interest rates, and tax and regulatory changes as among the key uncertainties influencing its short-term outlook.
APRA imposes additional capital requirement over governance failure
Separately, the Australian Prudential Regulation Authority (APRA) announced on Friday (6 November) that it would oversee a comprehensive assessment of how Macquarie Group calculated required capital for its non-bank businesses after identifying a breach of its Non-Operating Holding Company authority.
The regulator discovered during a recent capital review that Macquarie had miscalculated the capital required to support risks in the non-bank business, with the breach dating back to 2019.
Macquarie has corrected the understatement, and a $100 million governance overlay has been imposed, additional to the $500 million capital overlay applied to Macquarie Bank in 2021.
APRA deputy chair Therese McCarthy Hockey said Macquarie’s failure to detect and address the issue through its own controls fell short of the standards expected of a financial group of its size.
“Macquarie is one of the country’s largest financial groups and, as such, APRA expects it to have among the highest standards of governance, risk management and controls. Macquarie failed to identify and address this issue through its own governance and assurance processes, which falls short of APRA’s expectations,” she said.
[Related: Brokers thanked for Macquarie’s 28% mortgage growth]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.