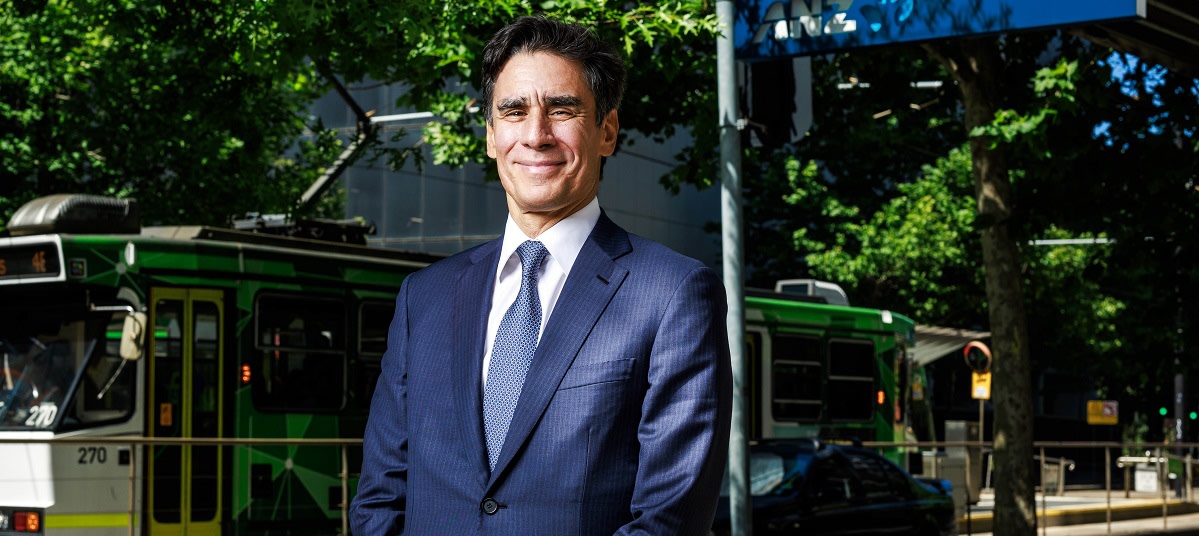
ANZ CEO Nuno Matos has said Bathla’s failure should prompt closer regulatory scrutiny beyond deposit-taking banks.
Australia and New Zealand Banking Group (ANZ) CEO Nuno Matos has urged regulators to examine whether efforts to protect bank depositors have shifted lending risks into Australia’s less transparent private-credit market, following the collapse of NSW developer Bathla Group.
In his first public comments on Bathla’s voluntary administration, Matos said regulatory policy needed to account for how tighter settings in one part of the financial system could redirect activity, and risk, elsewhere.
Speaking at The Australian Financial Review Asia Summit on Tuesday (15 September), the ANZ boss said regulators should not assess regulation solely through the resilience of deposit-taking banks.
“When we do regulation, when we do things, we need to take into account the secondary banks,” Matos said.
“If you regulate just a part of the system, by definition, the problem will show up in another place, and it might show up in a worse profile.”
Matos said much of the lending that supported Bathla’s expansion had moved outside the banking system as a way of limiting risk to depositors and added that the resulting question was whether investors and consumers could now be exposed to risks embedded in non-bank credit structures.
“Most of this lending went out of banking to protect bank depositors, so I’m intrigued, and I would like to make sure that there is no exposure from retail customers to these kinds of activities outside of the banking activity,” he said.
Limited threat to banks
While raising concerns about how risk is distributed through the financial system, Matos sought to distinguish Bathla’s failure from a threat to bank stability.
The Sydney-based developer entered voluntary administration in late August after running into severe cash flow pressure, with preliminary figures placing known creditor claims at about $3.4 billion.
The overwhelming majority, about $3.08 billion, was owed to secured lenders, highlighting the scale of the private-credit funding tied to the group’s projects.
Restructuring firm Teneo was appointed over Bathla’s main corporate entity, Universal Property Group, and related construction company Raj & Jai Constructions on 25 August.
Bathla’s collapse has attracted close market attention because it grew into a major residential developer without conventional bank funding underpinning its expansion.
The group has about 2,500 apartments under construction and a further pipeline of around 14,000 dwellings, creating uncertainty for purchasers, contractors, staff, lenders, and communities dependent on projects being completed.
Matos said the public reaction reflected Australia’s conservative approach to financial risk, but noted that occasional company collapses were an inevitable feature of the market.
“This kind of lending activity, for the most part, is not involving bank balances. So, first-order impacts I wouldn’t expect. Second-order impacts will also be quite limited, in my opinion,” he said.
“I’m not concerned at all for the banking system, in my opinion, and certainly not for ANZ.”
ASIC presses for transparency
Matos’ warning comes after ASIC chair Sarah Court used Bathla’s failure to reinforce the regulator’s concern about the opacity of Australia’s private-credit market.
Appearing before the parliamentary joint committee on corporations and financial services earlier this month, Court said the collapse had sharpened concerns around a sector that had grown rapidly, but remained difficult for regulators and investors to assess.
“There have been some troubling developments recently in the private credit sector, most notably with the recent collapse of Bathla,” Court told the committee.
“In our view, there is currently a lack of information and insight into wholesale private credit funds, and the limited information that we get in Australia is well behind that of similar jurisdictions.”
Court noted that the sector’s expanding role meant transparency needed to keep pace, allowing regulators and investors to better identify risk before borrower distress translated into fund-level liquidity pressure.
Bathla’s administration has already tested that proposition.
Both Centuria and CVS Lane have since restricted fund redemptions amid exposure to the developer’s projects, reiterating how impaired development loans can affect investor access to capital when underlying assets are illiquid.
Last week, the developer secured short-term support from five lenders, PAG, Ray White Capital, La Trobe Financial, RMBL, and Centuria Bass, while administrators pursue a longer-term arrangement.
Teneo confirmed on 7 September that 213 staff had been stood down, with the funding set to keep operations running for a fortnight, temporarily staving off liquidation.
[Related: ASIC puts private credit on notice after Bathla collapse]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.