The opposition wants a new regulatory balance, pairing growth ambitions with potentially tougher enforcement consequences.
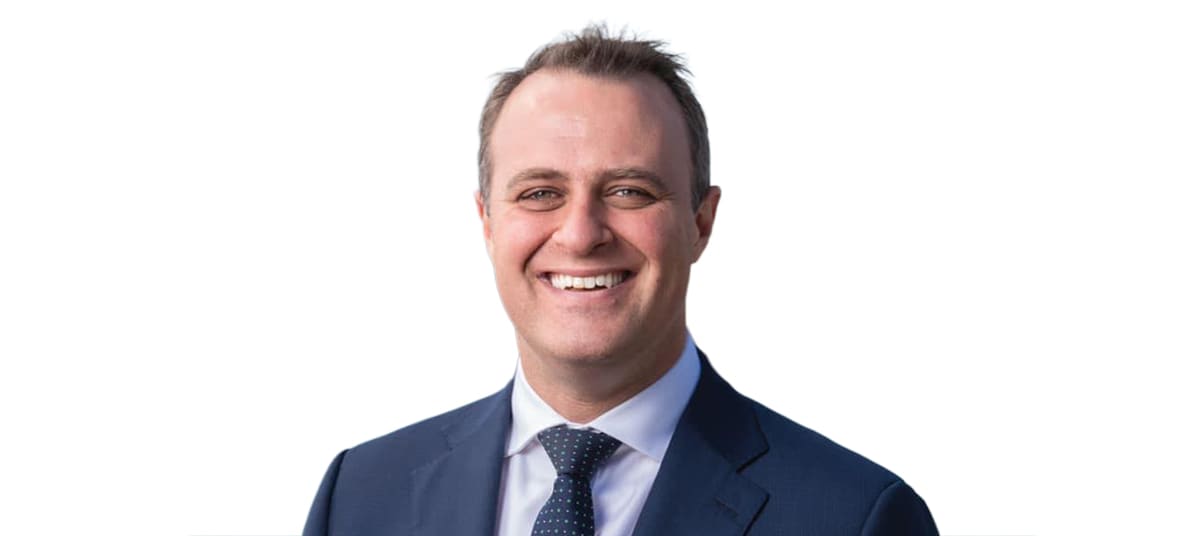
The Coalition has pledged an “attitudinal reset” at the Australian Securities and Investments Commission (ASIC) and the Australian Prudential Regulation Authority (APRA), with shadow treasurer Tim Wilson arguing that regulators were constraining growth and competition while flagging potentially heavier penalties for harmful breaches.
Speaking at the Australian Finance Industry Association (AFIA) conference in Sydney on Tuesday (20 October), Wilson called for a change in the incentives guiding financial regulators, arguing that their current settings encouraged them to prioritise reducing risk over managing it.
“We need an attitudinal reset to the role of our regulators. Our regulators respond to incentives like everyone else. Currently, regulators are tasked with minimising risk, and in some places compel it,” he said.
He added that regulators needed to weigh the commercial consequences of their decisions, warning that increasingly complex compliance requirements could make it harder for new businesses to enter the market.
“The incentive for regulators is to impose more complex regulation and costs on businesses. They lack an obligation to weigh decisions against the consequences of market entry and industry growth,” Wilson said.
“That needs to change. Regulators fulfil an important function in our economy, but it must be weighed against the consequences of their decisions.”
To give competition greater weight in regulatory decisions, Wilson said he was examining Singapore’s model of combining financial supervision with sector development responsibilities, potentially giving ASIC and APRA obligations to support expansion and innovation.
“I am interested in adopting the Monetary Authority of Singapore’s dual mandate as both a strict financial regulator as well as its sector development responsibilities,” he said.
“I am looking very closely at this model for regulation, to redress the imbalance of regulation from risk minimisation to risk management. In plain English, that means regulators like ASIC and APRA would have explicit obligations to help industry grow, compete and innovate.”
The proposal comes after Treasurer Jim Chalmers issued new statements of expectations for APRA and ASIC in July, directing them to support growth through proportionate, risk-based regulation.
Those instructions followed last year’s Economic Reform Roundtable, where excessive regulation was identified as a substantial drag on productivity.
Risk shifts into non-bank lending
Explaining the thinking behind his proposed reset, Wilson criticised the regulatory approach that followed the banking royal commission.
“In finance, we are living the consequences of regulation designed by lawyers from a royal commission that has focused on minimising risk, rather than managing it,” he said.
“The consequence of the Hayne royal commission has not removed risk, it has just relocated it. And prudential regulation has made it difficult for the big banks to manage risk as part of their book.”
Wilson’s criticism extends the Coalition’s scrutiny of financial regulators, with housing spokesman Andrew Bragg repeatedly challenging APRA’s three-percentage-point mortgage serviceability buffer,
Bragg has regularly argued that the requirement to assess borrowers at higher interest rates excludes prospective first home buyers (FHBs).
Turning to business lending, Wilson said that borrowers were consequently seeking funding from private credit and non-bank lenders, concentrating risk in those channels.
“So higher risk or lower security businesses gravitate to private credit and non-bank lenders. In the process, it concentrates risk and increases costs that are ultimately passed onto customers,” he said.
“This concerns me because we are currently in a finance environment where risk is concentrated and concurrently exposed to dramatic shifts in government policy – like tradies and developers are exposed to changes in SMSF lending, negative gearing, capital gains as well as the unfolding disaster of small business taxes on trusts.”
Having linked those exposures to government policy, Wilson argued that the response should be to spread risk more broadly across the financial system.
“These are problems brought on by government, but it creates specific risks for private credit and non-bank lenders where risk is concentrated,” Wilson said.
“The pathway through these problems is rebalancing of risk from concentrating it to distributing it because we expect rules and regulations not to fall for the false promise of mitigation toward management.”
Tougher penalties, proportionate regulation
Wilson also paired his push for a more growth-oriented regulatory approach with the prospect of heavier penalties when established operators breached requirements and caused harm.
“The trade-off for regulation that embeds risk management may be heavier penalties for breaches when harm is caused by established operators,” he said.
“There also needs to be a focus on proportionate impacts for smaller operators so regulation doesn’t become a barrier to entry. I want ASIC, APRA and the Reserve Bank to focus on enforcement, as part of a broader understanding that we need a ‘get to yes’ economy.”
[Related: How does ASIC evaluate ‘cheapest loans’?]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.