Industry bodies have welcomed ASIC’s new review of lending practices, while urging the regulator against excessively regulating mortgage and finance brokers.
Mortgage and finance industry associations have welcomed the Australian Securities and Investments Commission’s (ASIC) planned review of lender conduct across referrer, proprietary-banking and broker channels, while urging the regulator to focus any response on proven gaps rather than duplicating oversight already applied to mortgage brokers.
ASIC has flagged the work as part of its 2026–27 banking-sector supervisory agenda, with the review expected to start in the third quarter of the financial year.
It follows recent widespread mortgage-fraud revelations and places lender controls across the home-loan origination chain under examination.
The corporate regulator said its work would consider whether recent changes to banks’ remuneration frameworks, the use of referrers, and lenders’ monitoring of broker-originated lending could be creating conduct or consumer-outcome risks.
“We will commence a review into various aspects of lender conduct. This is likely to focus on the impact of the short-term variable remuneration changes for proprietary lenders introduced by banks in 2024, the use of referrers by lenders, and lender oversight of brokers,” ASIC said.
MFAA calls for ecosystem-wide response
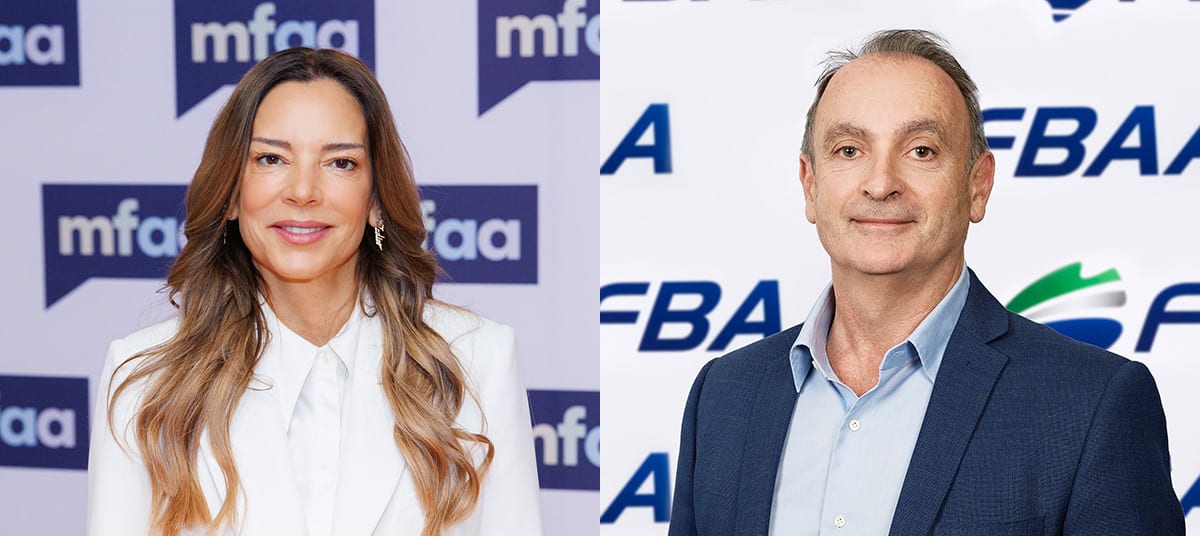
Mortgage & Finance Association of Australia (MFAA) chief executive Anja Pannek said the association supported ASIC’s increased attention on risks that could arise across interconnected mortgage-distribution channels, particularly where controls are inconsistent.
“We have been raising concerns about the risks associated with large-scale referrer arrangements for some time. As we saw during the Banking Royal Commission, large-scale referrer programs, particularly where there is inadequate due diligence, monitoring or oversight, can create significant vulnerabilities and avenues for fraud and poor conduct,” Pannek said.
Pannek added that recent mortgage-fraud cases had reinforced why controls must be assessed across the full lending ecosystem.
“Recent mortgage fraud matters have demonstrated the potential consequences when weaknesses in one part of the lending ecosystem are exploited. This cannot be viewed through the lens of any one distribution channel,” she said.
The MFAA chief also backed ASIC’s decision to review banks’ post-2024 short-term variable-remuneration arrangements for proprietary lenders, saying the issue warranted examination.
“We also welcome ASIC examining the impact of changes to banker incentives. Incentives influence behaviour, and it is appropriate that ASIC considers whether remuneration structures are creating unintended conduct risks or contributing to poorer consumer outcomes,” Pannek outlined.
The association has established a Fraud and Referrer Working Group bringing together lenders and aggregators to develop Referrer Risk Management Standards.
The proposed standards are expected to address referrer due diligence and onboarding, acceptable conduct and roles, customer contact, monitoring, red flags, escalation and termination processes.
“Fraud does not respect organisational or distribution boundaries. Strong controls within one organisation are only part of the solution if a high-risk individual can move elsewhere in the ecosystem without relevant information following them,” Pannek said.
Warnings mount against duplicating broker rules
While supporting ASIC’s supervisory work, Pannek said the review should distinguish between areas lacking effective controls and channels already subject to significant regulation.
“As ASIC undertakes this work, it is important that it distinguishes between areas where robust regulatory and assurance frameworks already exist and areas where there are genuine gaps or vulnerabilities,” Pannek noted.
She warned that a broad response should not result in additional obligations being imposed on the broker channel without a clear risk basis.
“Additional regulation should not simply be layered onto parts of the system that are already subject to substantial oversight. The focus must be on identifying where the real risks sit and addressing them,” Pannek stressed.
FBAA seeks balanced approach
Meanwhile, Finance Brokers Association of Australia (FBAA) chief executive Leo Gagic said the association had recently met ASIC representatives to discuss the importance of maintaining a proportionate focus.
Gagic said the FBAA supported efforts to find and remove misconduct but said ASIC’s work should also recognise that most brokers act ethically and in their clients’ interests.
“The FBAA recently met with representatives from ASIC to discuss the importance of maintaining a balanced focus as the regulator continues its review of lender oversight, referral channels, and broker conduct,” Gagic said.
“While we strongly support efforts to identify and remove bad actors from the industry, it is equally important to recognise the vast majority of brokers operate professionally, ethically and in the best interests of their clients.”
He said misconduct should be investigated and addressed, while reiterating that ASIC also had an opportunity to share examples of effective controls.
“ASIC also has a significant opportunity to highlight positive case studies and examples of best practice that emerge from its investigations and supervisory work,” Gagic said.
“Sharing what good looks like can provide valuable learning opportunities across the industry and help raise standards for everyone.”
Gagic added that a regulatory approach which identified wrongdoing while elevating high-quality conduct could improve outcomes across the market.
“As the industry continues to evolve, we encourage a regulatory approach that not only calls out wrongdoing but also shines a spotlight on excellence, strong compliance outcomes, and customer-first behaviour,” he said.
“Celebrating what is working well can be just as powerful as identifying what is not, helping brokers, lenders and consumers benefit from the lessons learned.”
[Related: Solo brokers lose ground as business pressures build]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.