ASIC is examining a further 24 private-credit funds while preparing enforcement action against practices it said had failed to keep pace with the sector’s rapid growth.
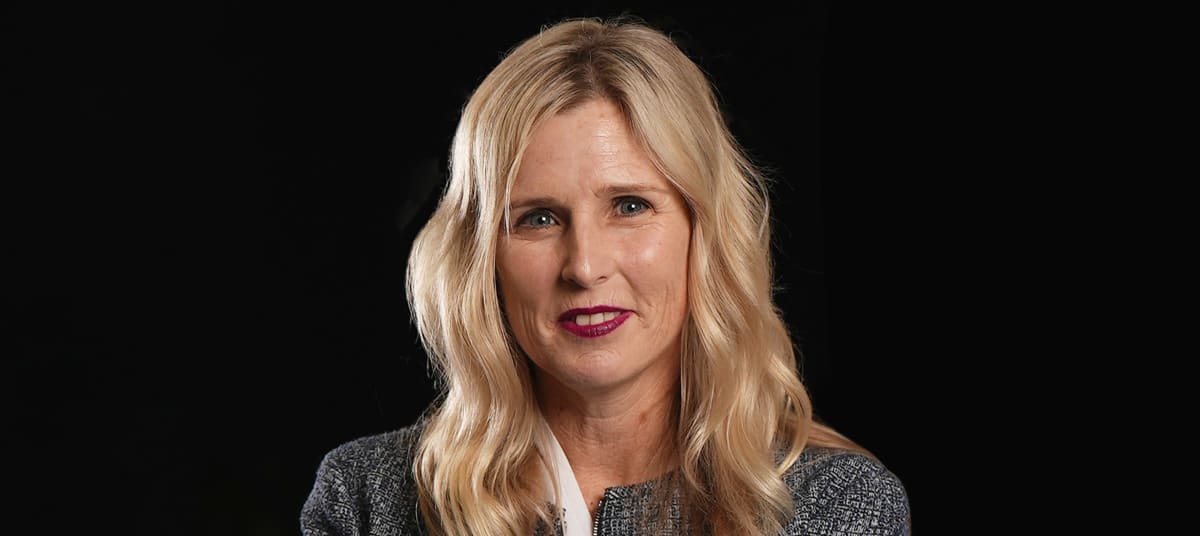
At CAFBA’s commercial property and development finance summit in Sydney on Tuesday (22 September), which was attended by The Adviser, Australian Securities and Investments Commission (ASIC) commissioner Simone Constant said the corporate regulator was actively reviewing more funds as it increased surveillance across wholesale and retail private credit.
The expanded work follows ASIC’s review of 28 private-credit funds and comes as the regulator has multiple enforcement investigations underway.
Constant said ASIC’s attention was firmly on disclosure, valuation, governance, conflicts, liquidity, and the consistency of information being presented to investors.
During her speech, Constant warned private-credit managers, boards, and distributors that they had until the end of the year to meet the regulator’s expectations or face compliance and enforcement action.
“We are definitely seeing stress fractures or cracks in the sector, that’s not a surprise,” Constant said.
“When you think about the strategic risk environment, growth and economic conditions more generally, one of our concerns about private credit is that at this scale, mix, and current concentration of property, this is untested in prior crises.”
ASIC widens surveillance
Constant said ASIC’s newer review work would go beyond product comparisons, with the regulator applying what she described as a more rigorous investor-style assessment to a further group of funds.
“Are we doing the mystery shopper tests? Actually, it’s not even mystery. We’re doing seriously deep-informed shopper tests,” Constant said.
“We’re looking very closely at another 24 funds who have some crossover, but not much crossover with some funds we looked at in the first 28.”
However, she made clear that ASIC also had active enforcement matters on foot.
“We have multiple enforcement investigations underway and are undertaking active surveillance across wholesale and retail funds,” Constant said.
Disclosure gap under spotlight
The commissioner also said Australian disclosure standards were lagging comparable offshore markets, particularly in the wholesale-fund segment.
“We are south of almost every comparable jurisdiction, and it’s important that this room knows it because we are sick of saying we want a level of disclosure,” she said.
“When you realise that we’re south of Switzerland in terms of the disclosures then I think you realise we’ve got a gap.”
Constant outlined that ASIC had found wide variation in core definitions and cautioned brokers against treating LVR as a sufficient stand-alone measure of credit risk.
“Overlay some questions, if someone says it’s okay because we’ve got a low LVR, something ASIC has really shone a light on is the canyon-wide variations in mission-critical definitions,” she said.
“I called out default, that is number one, when you see a difference in some funds, in some cases it’s a certain number of days past due, it’s pretty orderly.
“In others, you’re basically having to think about whether a bailiff is going in to get chairs out of properties before you really have to call default.”
She also pointed to potentially material differences in the way LVRs are calculated.
“We have seen LVRs that are being assessed on an as-complete LVR in a five-year construction period,” Constant said.
Managers back standards uplift
During a panel discussion with the commissioner on the private-credit sector, Daniel Mote, head of capital solutions and corporate affairs at Qualitas, said a stronger disclosure regime would assist the industry’s more established participants as well as investors.
“From an industry standards uplift, it’s something which we have been crying out for as an industry in terms of the better players,” he said.
“Being able to sit down and explain to an investor very clearly and concisely where your fund and where your strategy is ranking compared to other strategies is really difficult when you don’t have consistent and effective disclosure across other products.”
Mote welcomed ASIC’s reports and standards developed by the Financial Services Council, saying they could support a broader lift in market practice.
“We think they’re going to drive a greater uplift from the industry. We hope, and we again encourage everyone to be adopting that,” he said.
Yet, he acknowledged that applying a consistent disclosure framework would be complex due to private credit covering a broad range of lending activities and underlying assets.
“How you adopt and overlay consistent and effective disclosure across the industry is going to be a lot of work for everyone, but it’s something which we absolutely need to tackle,” he said.
Meanwhile, Tom Cranfield, executive director of Zagga Group Australia, said transparency and investor stewardship should be considered fundamental obligations for fund managers.
“Being asked to transparently run your business, to work for your investors, to maintain that stewardship and fiduciary duty is the bare minimum of expectations for a manager,” Cranfield said.
He said the industry needed to respond quickly to ASIC’s expectations, even if changes would require an ongoing implementation process.
“But we need to listen to the regulator, and we need to get these things right,” he said.
“Whether or not they were done exactly as they should be, in line with an industry standard, is a fair and reasonable question to be asked, but I do agree we should be moving ourselves quickly to get to the point of reflecting those things.”
Remara products halted by ASIC
ASIC’s broader warnings were accompanied by immediate action against three private-credit products offered by Melbourne Securities Corporation Limited under the Remara Cash Management Fund.
On Tuesday, ASIC issued interim design and distribution obligations stop orders against the fund’s six-month fixed and variable account, 12-month fixed and variable account, and at-call account.
The regulator said the products’ target market determinations contained deficiencies and raised concerns that retail investors could be exposed to products that may not suit their objectives, financial situation, or needs.
The interim orders prevent MSC from dealing in fund interests, issuing product disclosure statements, or giving general financial product advice recommending the products to retail clients. They are valid for 21 days unless revoked earlier.
Constant told the event that ASIC had repeatedly provided notice of its concerns and expected the market to act before its deadline passed.
“The clock is ticking, we will do what we say we’re going to do,” Constant said.
“We gave you till the end of the year as an industry to rise to that expectation, otherwise, we’ll be using all of our regulatory toolkit, which we are getting ready to use, and that will include absolutely compliance and enforcement action.”
[Related: ‘Beyond warning’: ASIC tells private credit to expect ‘enforcement action’]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.