
The MFAA’s membership has expanded, with the association revealing that inquiries had grown substantially, and that advice was dominating sampled support interactions.
The Mortgage and Finance Association of Australia (MFAA) grew its membership by 4.1 per cent in FY2025–26, while inbound telephone inquiries increased by about 11 per cent.
Its 2025–26 annual report recorded 16,842 members at 30 June 2026, up from 16,172 a year earlier, although growth moderated from the previous financial year’s 5.17 per cent.
Mortgage and finance brokers comprised 97 per cent of members, and the membership’s gender split was 71 per cent male and 29 per cent female.
The association said the membership services team fielded 7,149 inbound telephone inquiries, with almost 80 per cent of a sample of interactions concerning advice, guidance, clarification, or helping brokers navigate an issue, rather than transaction processing.
It added that more than 90 per cent of inquiries were resolved on first contact.
Outbound calls, meanwhile, exceeded 6,170, about 32 per cent above FY2024–25 levels, as the association stepped up proactive engagement.
The expansion coincided with brokers facilitating a record 81.6 per cent of new residential home loans in the June 2026 quarter, according to MFAA-commissioned Cotality data.
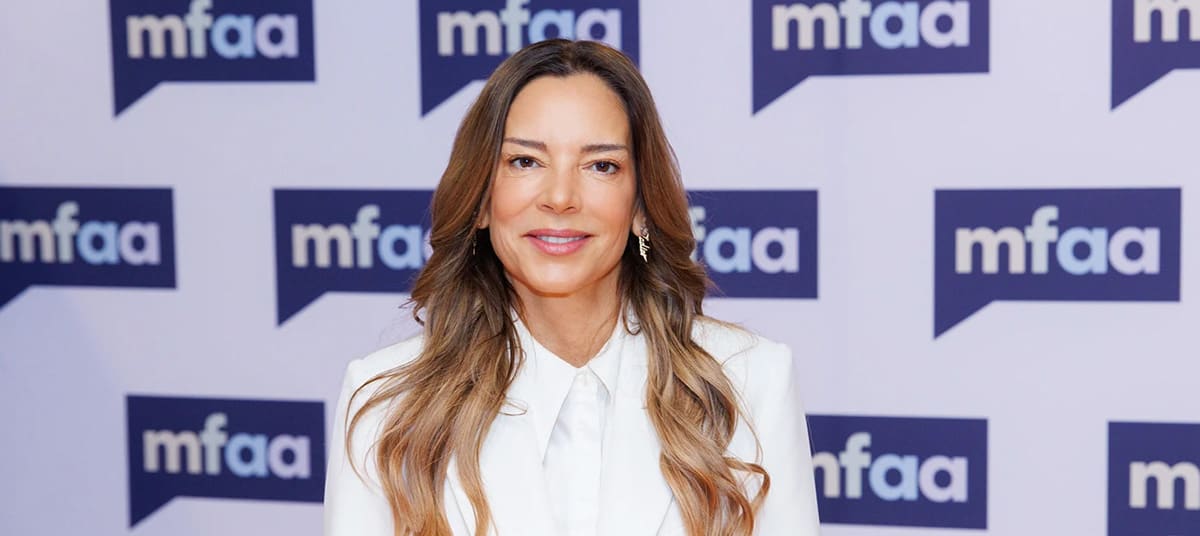
MFAA chief executive Anja Pannek said growing consumer reliance on brokers underscored the importance of investing in businesses, capabilities, and professional standards.
“More Australians are choosing brokers to help them understand their options and navigate important financial decisions,” Pannek said.
“That trust is earned through the work our members do every day. Our role is to support them with strong advocacy, practical education and resources.”
Advocacy and professional standards
The MFAA said it lodged more than 25 formal submissions over the year and engaged with the federal government, opposition, Treasury, Australian Securities and Investments Commission (ASIC), Australian Prudential Regulation Authority (APRA), Australian Financial Complaints Authority (AFCA), and other agencies.
Its recommendations addressed the Consumer Data Right (CDR), home lending competition, housing affordability, regulatory costs, the Compensation Scheme of Last Resort (CSLR), cyber resilience, and scams.
The report also included an update on the Mortgage Finance Professional Australia designation, developed with RMIT Online and described by the MFAA as Australia’s first professional mortgage broker designation.
By June, the association said it had received 111 applications, with 35 brokers graduating with the designation.
Launched in July 2025, the designation targets experienced members.
Applicants must have at least five years’ broking experience, 250 settled loans, a diploma of finance and mortgage broking management, current continuing professional development, and two professional endorsements.
The program combines personal leadership, customer engagement, and business management with an elective course covering specialist lending.
Revenue was broadly steady at $11,506,273, while expenses increased 2 per cent to $11,361,573, leaving a $144,700 excess of revenue over expenses.
Pannek identified professional standards and recognition of brokers’ contributions as key priorities for the association’s ongoing investment.
“We will continue investing in professional standards, helping members embrace technology and ensuring the value of mortgage and finance brokers is understood by consumers and decision makers,” Pannek said.
[Related: Australia’s broking trail commissions ‘unusual’ by global standards]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.