
A bank chief economist has warned that another interest rate shock could significantly expose financial vulnerabilities and threaten Australia’s long-running housing boom.
Judo Bank’s chief economic adviser, Warren Hogan, has forecast Australia’s cash rate will reach 5.35 per cent, warning that persistent inflation and rising government spending could trigger a damaging interest rate shock.
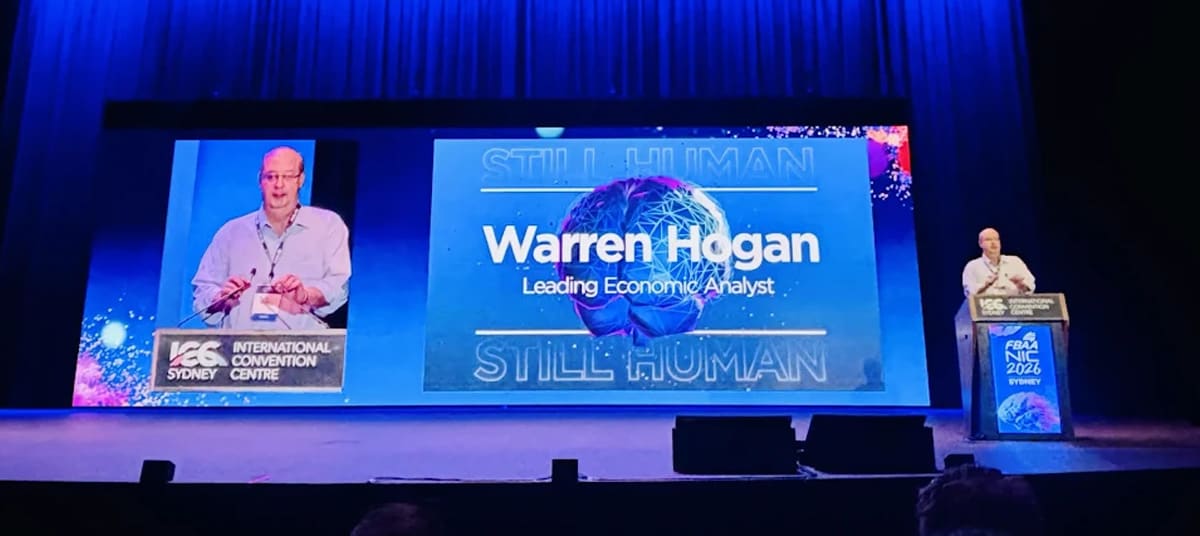
Speaking at the Finance Brokers Association of Australia’s (FBAA) 2026 national industry conference on Thursday (29 October), which was attended by The Adviser, Hogan said further monetary tightening could expose financial vulnerabilities left unresolved after the first post-pandemic rate shock.
Hogan, who is also the managing director and founder of EQ Economics, outlined a higher-rate outlook while warning that the consequences could extend beyond the immediate pressure on borrowers.
“I’ve got the cash rate going to 5.35 per cent. So look, we’re in a dangerous situation,” he said.
His forecast would represent another 75 basis points of tightening from the current 4.60 per cent cash rate.
All four major banks now expect a quarter-point increase at the Reserve Bank of Australia’s (RBA) meeting on Tuesday (3 November), which would lift the official cash rate to 4.85 per cent, its highest level since 2008.
The Commonwealth Bank of Australia (CBA) and National Australia Bank (NAB) abandoned their expectations of an extended hold on Wednesday, joining Australia and New Zealand Banking Group (ANZ) and Westpac in forecasting a November increase following the September inflation release.
The Australian Bureau of Statistics (ABS) reported annual headline inflation of 4.3 per cent in September, up from 4 per cent in August, while annual trimmed mean inflation on the quarterly measure reached 3.7 per cent, up from 3.6 per cent.
“This is potentially the start of the second great interest rate shock after the pandemic, and because I think there’s still a lot of vulnerable financial structures sitting out there from the first one, this one’s going to hurt,” Hogan said.
Government spending could deepen the tightening cycle
Hogan’s forecast was accompanied by a more severe warning: without a reduction in government spending, the RBA could be forced to raise rates more frequently than his immediate outlook suggested.
“The RBA is going to do at least one more, probably a couple more. The thing is, if the governments of Australia don’t start pulling back, the RBA might have to do five or six more hikes, no matter what’s going on,” he said.
Central to Hogan’s argument was a mismatch between the pace of government spending and the weaker overall economic growth he believes is necessary to bring inflation under control.
“So what are our governments doing, they contribute about a third of the economic growth, the state and federal budgets handed down in the middle of this year have an average projected real spending growth of about 3 per cent,” he said.
“That means for that third of the economy, they’re taking up more than their fair share, and for the rest of us, the private sector, consumers, business, we’ve probably got like 1.2, 1.3 per cent.”
Hogan argued that the constraint became more pronounced when factoring in the RBA’s need to keep growth restrained while inflation remained elevated.
“But here’s the sting of the tail: we’ve got inflation well above target, and the RBA has been saying we actually have to grow the economy sub-par for an extended period of time to get inflation to target,” Hogan said.
“So we actually probably have to grow the economy by one or one and a half, and the governments of Australia are growing 3, that means the rest of us probably get zero, and hence why the RBA is moving the way they are.”
Hogan called on governments to use their own policy settings to reduce pressure on demand.
“Why don’t the governments of Australia, which have literally thousands of different levers they can pull, just pull a few back and take that pressure off interest rates,” he said.
He also pointed to the apparent resilience of household consumption, adding that the significance of that tenacity was that the economy had not weakened sufficiently to remove the need for further tightening.
“Then household consumer spending, it doesn’t look like there’s anything that’s negative happened this year, I don’t actually believe these numbers, how strong the consumer spending numbers have been,” he said.
“The rate hikes, the war, the energy shock, the budget, another energy shock coming back now, and consumers continue to spend, that’s why the RBA is hiking because the economy is not slowing enough.”
Hogan questions the RBA’s earlier inflation response
The economist’s criticism also extended beyond government budgets to the RBA’s handling of the inflation cycle, questioning whether its effort to balance inflation control against the economic costs of higher rates had ultimately prolonged the problem.
“It also complicates how to manage the economy, the RBA’s narrow path, it’s actually proven to probably be the exact opposite of what they should have done,” he said.
“In a world of high inflation, and this is a world of high inflation, they probably should have gone harder than normal and nipped this in the bud, not gone softer and let it linger, because as we see right here today, we’re in trouble.”
Discussing the possible level of interest rates needed to constrain rising inflation, Hogan offered a calculation based on a 2 per cent real interest rate and 3.7 per cent core inflation.
“If our real rate has to go back to our GDP growth, which at the moment we can only grow at about 2, but right now 2 per cent real rate, with core inflation at 3.7, what’s that for a cash rate, 5.75 per cent,” he said.
“Glenn Stevens in 2007, when we had our last serious inflation threat, he had to take the cash rate to 7.25 per cent, and this is far, far worse than that.”
Housing concerns move beyond a temporary downturn
Hogan also said the prospect of further tightening had changed his assessment of the housing downturn, prompting greater concern about both the immediate price adjustment and the market’s longer-term trajectory.
“I’ve been quite benign about this housing downturn. I’m now getting worried,” he said.
“If we get away with a peak-to-trough fall in the national house price of about 10 per cent, I think we’ll get through that, but at the moment, there’s flashpoints in the construction sector, for example, but I think the question now is, well, are we actually at the end of this 30-year great housing boom?”
His more far-reaching warning concerned the interaction between household indebtedness, vulnerable financial structures and the possibility that property values would take longer to recover than buyers had become accustomed to.
“Because of the fact that we’ve got so much household debt, other financial structures are looking very vulnerable,” Hogan said.
“The point I’m getting at is that that 30-year boom could be over, we might not see prices go to new highs for a couple of years, and in real terms, measured with adjusting for inflation, it might not happen for 20 years.”
Referring to a comparison of real house prices since 1982 with real household income per person, he also questioned the valuations underpinning the market.
“If you try and value housing, this is real house prices since 1982, if you measure it against real household income per capita, it’s telling us that house prices are double what they should be, but we all know affordability is at least 20 per cent too much,” he said.
“We are talking about a world where house prices are not going to deliver the same sort of real gains that we’ve seen the last 30 years.”
[Related: Mortgage repayments claim more than 50% of family income]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.