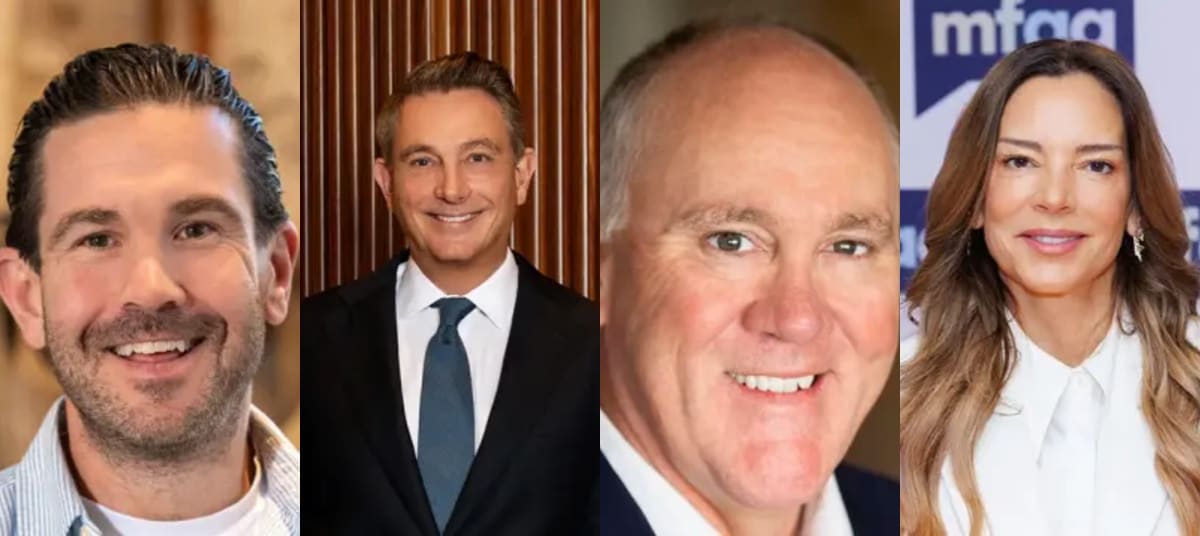
Industry leaders have backed stronger standards while warning that price alone cannot settle every borrower’s mortgage choice.
Mortgage broking associations and aggregators have stressed that cheaper loans are not always the most suitable, while supporting the Australian Securities and Investments Commission’s (ASIC) push for clearer justification of higher-cost recommendations following its best interests duty (BID) review.
The Mortgage and Finance Association of Australia (MFAA), Finance Brokers Association of Australia (FBAA), Australian Finance Group (AFG), Loan Market Group (LMG) and Lendi Group welcomed the findings, yet argued that in addition to price, borrower circumstances, credit policies, features and approval deadlines also influenced which loans deliver the best outcomes for borrowers.
Their responses nevertheless acknowledged that those considerations must be supported by evidence, with aggregators outlining plans to review practices, strengthen training and improve complaints handling.
Released on 13 October, ASIC’s Report 840 examined 13 credit licensees across eight major aggregator groups responsible for approximately two-thirds of broker representatives.
It identified weaknesses in recommendation records, supervision, complaints handling and data systems.
Seven groups reported that the lowest-cost loan was not recommended in more than 20 per cent of cases between April 2023 and March 2025. However, their data coverage and cost calculations differed, and the finding did not establish that those recommendations breached BID.
Connective Group legal counsel Daniel Oh said the review recognised the compliance arrangements already established across the sector, while providing a basis for addressing their shortcomings.
“ASIC’s review provides a valuable opportunity to build on the industry’s existing practices and strengthen outcomes for clients. It’s encouraging that the licensees reviewed generally had processes designed to support compliance, while the findings identify areas where those processes need to improve,” he said.
Price matters, but circumstances differ
MFAA chief executive Anja Pannek argued that scrutiny of individual loan costs should sit alongside recognition of broking’s contribution to competition, without diminishing the importance of price.
“Price absolutely matters. Consumers should have confidence that their broker has considered the available options and can clearly explain why a particular loan is in their best interests. At the same time, the lowest-cost loan is not necessarily the right loan for every borrower,” Pannek said.
FBAA chief executive Leo Gagic similarly welcomed ASIC’s recognition that considerations beyond cost can inform recommendations, describing it as acknowledgement of brokers’ judgement and understanding of customers.
“Competitive pricing matters, and brokers will always consider it. But every customer has different circumstances, and a broker’s value comes from understanding those needs and helping them find an appropriate loan,” Gagic said.
“For example, a self-employed customer may need a low doc loan because of the income documentation they can provide. It may not be the cheapest option, but it can enable them to secure a loan suited to their circumstances.”
Gagic also welcomed the finding that brokers did not appear to be favouring lenders paying higher commissions, while stressing that explanations and documentation should demonstrate why additional costs were justified.
Oh said assessing suitability required an understanding of the individual borrower, with any decision to recommend a more expensive product supported by a clear explanation.
“Best interests is about understanding each client’s circumstances and recommending a loan that meets their needs. Cost is a key consideration, alongside factors such as loan features, eligibility, and the ability to meet a settlement deadline. Where a higher-cost loan is recommended, brokers need to clearly demonstrate why it is in that client’s best interests,” Oh told The Adviser.
AFG chief executive David Bailey told The Adviser that competitive rates remained central to broking, but added that recommendations also needed to account for approval prospects, required features and timing.
“A broker should be able to show every customer how they compared the market and why the loan they’ve chosen suits that customer’s needs and goals,” he said.
“But a home loan is more than its headline rate. A broker’s job is to find a loan the customer can actually be approved for, on a timeframe that works for them, with the features they need.”
He said that an apparently cheaper product could fail to deliver the outcome sought by the borrower.
“Credit policy fit, borrowing capacity, product features and approval speed all shape the choice of lender and product. A loan that looks cheaper on paper offers little value if the lender’s policy doesn’t suit the borrower’s circumstances, or if it reduces how much they can borrow,” he said.
Bailey added that fixed settlement deadlines could introduce financial risks that rate comparisons did not capture.
“When an approval is time-critical, such as a purchase with a fixed settlement date, the cost of a delay can be significant and won’t show up in a rate comparison. Missing settlement can mean penalty interest, extra costs and, in the worst cases, losing the property and the deposit,” Bailey said.
Higher costs, stronger evidence
The duty, which commenced in January 2021, requires mortgage brokers to act in consumers’ best interests. ASIC’s review found generally established compliance processes, but some higher-cost recommendations lacked clear supporting reasons.
Bailey acknowledged those shortcomings and said the strength of the explanation should reflect the size of the price difference.
“Where a broker recommends a loan that isn’t the cheapest, the reasons should be clear, documented and explained to the customer, and the bigger the price difference, the stronger that explanation needs to be. AFG will keep working with our brokers, and with ASIC, to make sure that happens consistently,” he said.
AFG is assessing the findings against its documentation and complaints practices.
Meanwhile, LMG executive director and chief executive Ewen Stafford told The Adviser that BID remained the industry’s “greatest market differentiator”, adding that it “must continue to serve as our collective north star”.
However, he stressed that price alone often did not determine the most suitable recommendations for borrowers, identifying offsets, debt consolidation and settlement timing as potential reasons for selecting higher-cost products.
“While the report highlights product cost as a primary consideration, this is not the sole factor in determining the right outcome for every client,” Stafford said.
“A higher-cost loan may be the only option that delivers critical features, such as offset functionality, debt consolidation, or enables the client to meet a tight settlement timeline.”
He also stressed that departures from the cheapest option needed compelling records linked to the customer’s requirements.
“BID does not require recommending the cheapest loan in every instance, but higher cost requires higher evidence,” he said.
“The ASIC report emphasises that when you recommend a product that is not the cheapest option, the quality and clarity of the documented rationale are critical to evidence that you have complied with BID and recommended the best product for client’s specific needs.”
Oh said Connective’s expectations also extended to presenting suitable alternatives and making the advantages and disadvantages of a recommendation clear to the customer.
“Our message to brokers remains consistent: document the reasons behind your recommendations, present a choice of suitable options wherever possible, and clearly explain the benefits and trade-offs to the client,” he said.
“Connective is continuing to invest in practical support for our members, including tools in Mercury Nexus, to help brokers meet their best interests duty. These tools support brokers’ judgement and documentation, with brokers remaining responsible for reviewing the information and ensuring it reflects their client’s circumstances.”
Yellow Brick Road chief risk and compliance officer David Flynn said the group had already implemented, or made substantial progress on, many of the improvements identified in the report.
He welcomed ASIC’s assessment of existing industry processes and said further investment would support ongoing improvements.
“ASIC's report is welcome as it supports the continued strengthening of consumer outcomes across the mortgage broking industry and it's encouraging to see their overall conclusion that the industry's processes support BID compliance and are aligned with ASIC's guidance," Flynn said.
"Yellow Brick Road is already well positioned relative to the findings in the report, with many of the report's identified improvement opportunities already implemented, completed or well-advanced.
"The report sets out a best-practice roadmap of continuous improvement for the whole industry, and it's a roadmap we endorse, which is why we've made and will continue to make significant investment into the key themes identified by ASIC.”
Lendi Group co-founder and chief executive Sebastian Watkins supported the findings and added that regulatory reviews “helped strengthen industry standards and customer confidence in mortgage broking”.
“ASIC’s report reinforces the importance of prioritising cost and clearly demonstrating why a recommendation is in each customer’s best interests, particularly where a higher-cost loan is recommended,” Watkins said.
He added that the group would translate the review into guidance across its two brands.
“We will provide our Aussie and Lendi broker network with detailed guidance on the findings and incorporate these lessons into ongoing training, reinforcing our expectations for customer-specific recommendations, documented reasoning and prompt referral of all complaints to our dedicated complaints team,” Watkins said.
Complaints remain part of the response
ASIC also found that complaints were underreported and generally handled more compliantly when licensees managed them directly rather than leaving them with representatives.
Stafford encouraged referral to LMG’s complaints team and said the group would strengthen systems, data tools and education while engaging with ASIC and its broker community.
Pannek pointed to relatively low complaint volumes and limited exposure to Compensation Scheme of Last Resort (CSLR) claims, but rejected complacency.
“Strong consumer protections and strong competition work together to deliver better outcomes for borrowers. That level of consumer choice also brings significant responsibility. As the industry grows, maintaining trust means continuing to review what we do, responding where improvements are needed and keeping good consumer outcomes at the centre,” she said.
She supported better complaint identification, recording and resolution processes, while calling for regulatory expectations proportionate to risk.
“ASIC has identified opportunities to strengthen how complaints are identified, recorded and resolved. We support practical improvements in these areas, while ensuring regulatory expectations remain proportionate to the risks involved and focused on delivering better outcomes for consumers,” Pannek said
[Related: How does ASIC evaluate ‘cheapest loans’?]
Want to see more stories from trusted news sources?
Make The Adviser a preferred news source on Google.
Click here to add The Adviser as a preferred news source.