


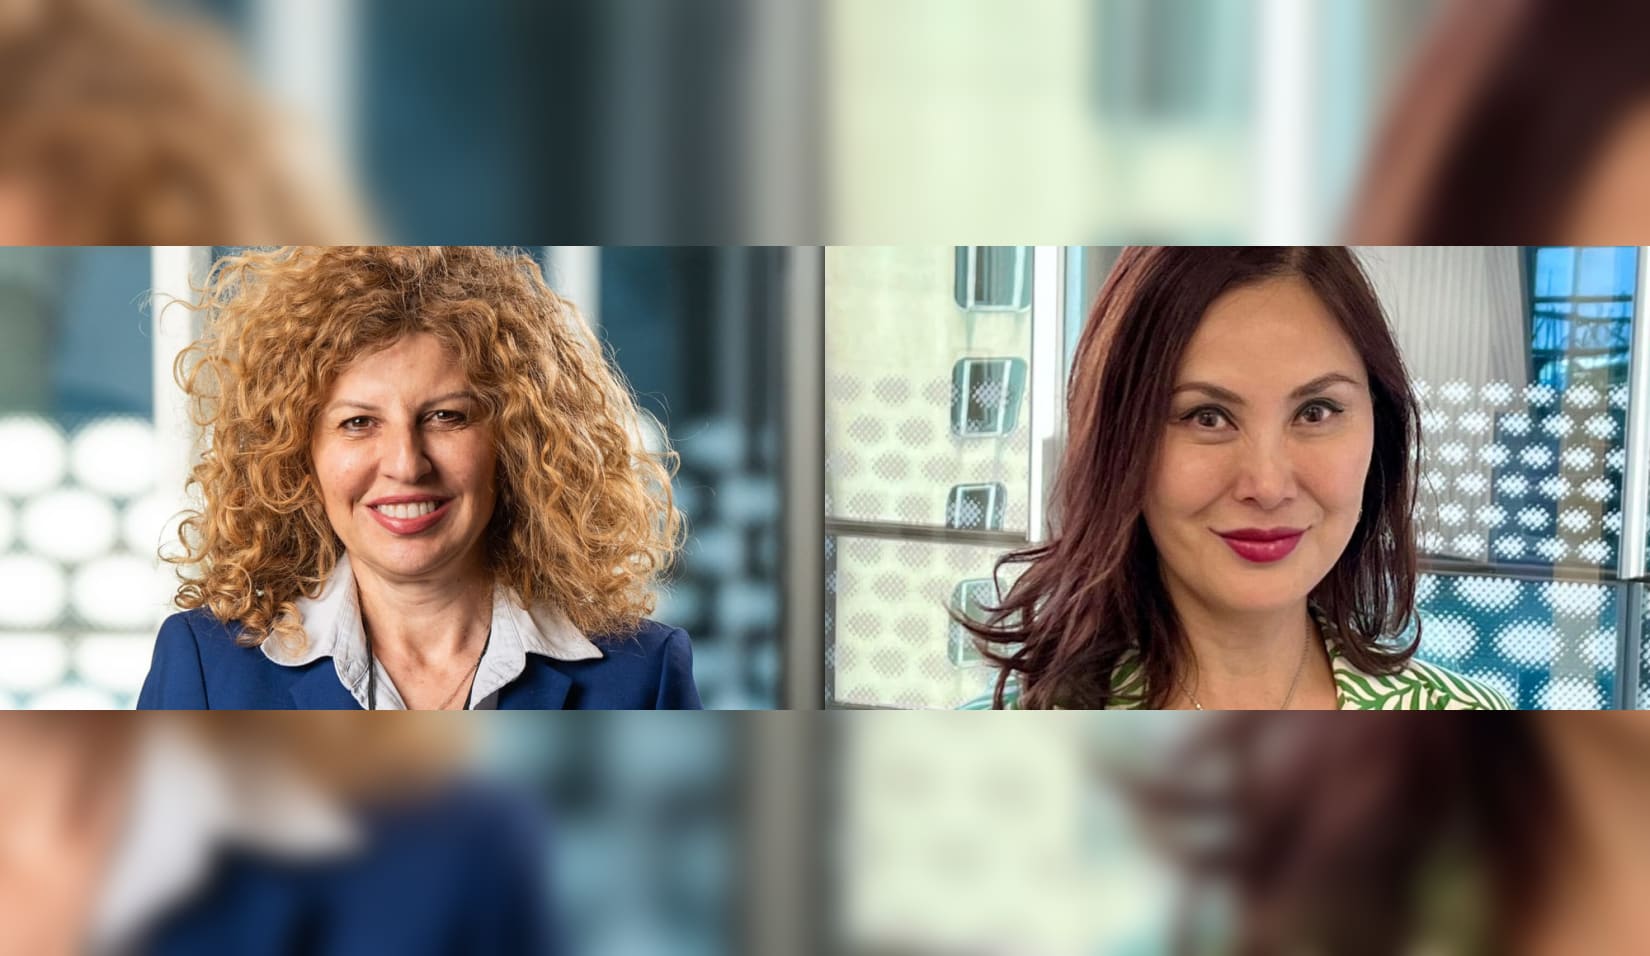
By:
Bridget Sakr
Co-founder and director
Kit Wong
National Sales Manager
Bridget Sakr (BS): Granite was established to offer brokers solutions for prime borrowers who don’t fit the criteria set by banks and other lenders. We provide a range of innovative products that respond to the needs of the market at any given time.
We started by offering lending to young professional borrowers coming out of university with limited savings, and have also developed a strong presence in the self-managed super fund (SMSF) space.
Now, we’re responding to another challenge in the Australian housing market with our 40-Year Extended Home Loan for both owner-occupiers and investors. At Granite Home Loans, we try to identify what borrowers need to ensure we develop the right solutions for our brokers and their clients.
BS: Saving is a real barrier at the moment, because the cost of living and rents are high.
But the other hurdle is affordability and servicing pressures. We’ve had four consecutive rate rises this year, which has put further pressure on existing and prospective home buyers trying to enter the housing market, particularly when you combine this with serviceability buffers.
The 40-year home loan is about improving access to credit. It helps people access finance and makes it more affordable for them, which is why we’ve introduced this product.
Kit Wong (KW): Where we see the 40-year extended term really helping consumers is with affordability. With all the regulations and restrictions, even consumers who can stretch their budget to meet standard servicing requirements often can’t afford the home they actually want. Instead, they have to compromise and buy a home they’re told they can afford.
KW: Some other competitors cap their 40-year-term products at an 80 per cent loan-to-value ratio (LVR), but we’ve enabled ours to go up to 95 per cent LVR, including risk fees.
The product also extends beyond purchases. We offer it for refinancing and construction, giving consumers a lot more flexibility in this market. We’ve also opened it up to investors, allowing up to 10 years of interest-only repayments for investors and five years for owner-occupiers. This gives borrowers a bit more breathing space if they need it.
By offering 10 years of interest-only repayments at potentially up to 95 per cent LVR, I think we’re also encouraging investors back to the market, particularly in the construction space.
The way we’ve developed it, it’s also not restricted to individuals. Individuals can apply in their own name, but we can also accommodate borrowing through trusts and companies.
KW: Granite is a prime lender, so brokers know that when they submit a loan application, it will be fully documented. The only requirements are that the consumer has a good repayment history. Beyond that, they need to be able to service the loan.
For owner-occupiers, we assess serviceability over a 35-year term, while the loan itself has a 40-year repayment term. This means eligible owner-occupiers can access the full 40-year term up to age 45, taking them to the product’s maximum age of 85 by the end of the loan term. The loan is available up to the age of 50 on a 35-year home loan term.
For investors, there are no age restrictions. We simply ask them to provide an exit strategy if they are over the age of 55, outlining how they could sell the investment property, allowing them to access the full 40-year term.
“For owner-occupiers, we assess serviceability over a 35-year term, while the loan itself has a 40-year repayment term.”
- Kit Wong
“For owner-occupiers, we assess serviceability over a 35-year term, while the loan itself has a 40-year repayment term.”
- Kit Wong
For owner-occupiers, we assess serviceability over a 35-year term, while the loan itself has a 40-year repayment term. This means eligible owner-occupiers can access the full 40-year term up to age 45, taking them to the product’s maximum age of 85 by the end of the loan term. The loan is available up to the age of 50 on a 35-year home loan term.
For investors, there are no age restrictions. We simply ask them to provide an exit strategy if they are over the age of 55, outlining how they could sell the investment property, allowing them to access the full 40-year term.
KW: There’s a perception that we’re encumbering consumers for longer and forcing them to make more repayments, which means paying more interest. But I think that’s a different way of looking at it. We’re entering the market with the aim of helping people buy a home.
This is a serviceability pathway to help consumers get into the housing market, and the product has a variable interest rate. As with any other variable rate home loan, clients are not locked into a 40-year term – they can make unlimited early repayments to repay early and shorten their loan term or refinance to a shorter loan term.
BS: You’re assessing borrowers at a point in time. When they’re under pressure to enter the housing market and access credit because of interest rate rises and the cost of living, this product offers a solution to help them get into housing by improving their serviceability at that point in time.
Circumstances change all the time, and borrowers can refinance if their situation improves.
“As with any other variable rate home loan, clients are not locked into a 40-year term – they can make unlimited early repayments to repay early and shorten their loan term or refinance to a shorter loan term.”
- Kit Wong
“As with any other variable rate home loan, clients are not locked into a 40-year term – they can make unlimited early repayments to repay early and shorten their loan term or refinance to a shorter loan term.”
- Kit Wong
This is a serviceability pathway to help consumers get into the housing market, and the product has a variable interest rate. As with any other variable rate home loan, clients are not locked into a 40-year term – they can make unlimited early repayments to repay early and shorten their loan term or refinance to a shorter loan term.
BS: You’re assessing borrowers at a point in time. When they’re under pressure to enter the housing market and access credit because of interest rate rises and the cost of living, this product offers a solution to help them get into housing by improving their serviceability at that point in time.
Circumstances change all the time, and borrowers can refinance if their situation improves.
BS: If the pressures we’re currently seeing continue, I think extending loan terms will become more prevalent. It’s a very difficult time for consumers, so I think lenders across the mortgage market will increasingly consider this option.
It’s a flexible option, and Granite Home Loans has always aimed to provide flexible lending solutions.
“If the pressures we’re currently seeing continue, I think extending loan terms will become more prevalent.”
- Bridget Sakr
“If the pressures we’re currently seeing continue, I think extending loan terms will become more prevalent.”
- Bridget Sakr
BS: If the pressures we’re currently seeing continue, I think extending loan terms will become more prevalent. It’s a very difficult time for consumers, so I think lenders across the mortgage market will increasingly consider this option.
It’s a flexible option, and Granite Home Loans has always aimed to provide flexible lending solutions.
Tune in to hear more!
Find out more about Granite Home Loans’ new 40-Year Extended Home Loan in the In Focus podcast episode, 'In Focus: Extending home ownership reach', here:
Bridget Sakr
Co-founder and director
Kit Wong
National Sales Manager
Greenlink

 1 min read