Federal budgets rarely pass without a big announcement or two, but property investors could be forgiven for feeling as though the rug had been pulled out from underneath them.
Changes to the tax treatment of negative gearing and the capital gains tax (CGT) discount have forced many investors to rethink their strategies, while restrictions around borrowing residential property through a self-managed super fund (SMSF) have added a further layer of complexity.
At the same time, elevated borrowing costs and stretched household budgets are adding another hurdle for property investors considering further debt.
But is the outlook really as bleak as it appears? Not necessarily.
The question may not be whether investors will continue to buy property, but how they will do so in a market where some of the traditional incentives are no longer as attractive.
For brokers, that could create an opportunity to help their investor clients rewrite the property investment playbook, rather than abandon it altogether.
Dipping demand
While the dust is still very much settling in terms of what reforms mean for the broader market, the most recent lending indicators release from the Australian Bureau of Statistics (ABS) has pointed to a pullback in investor activity.
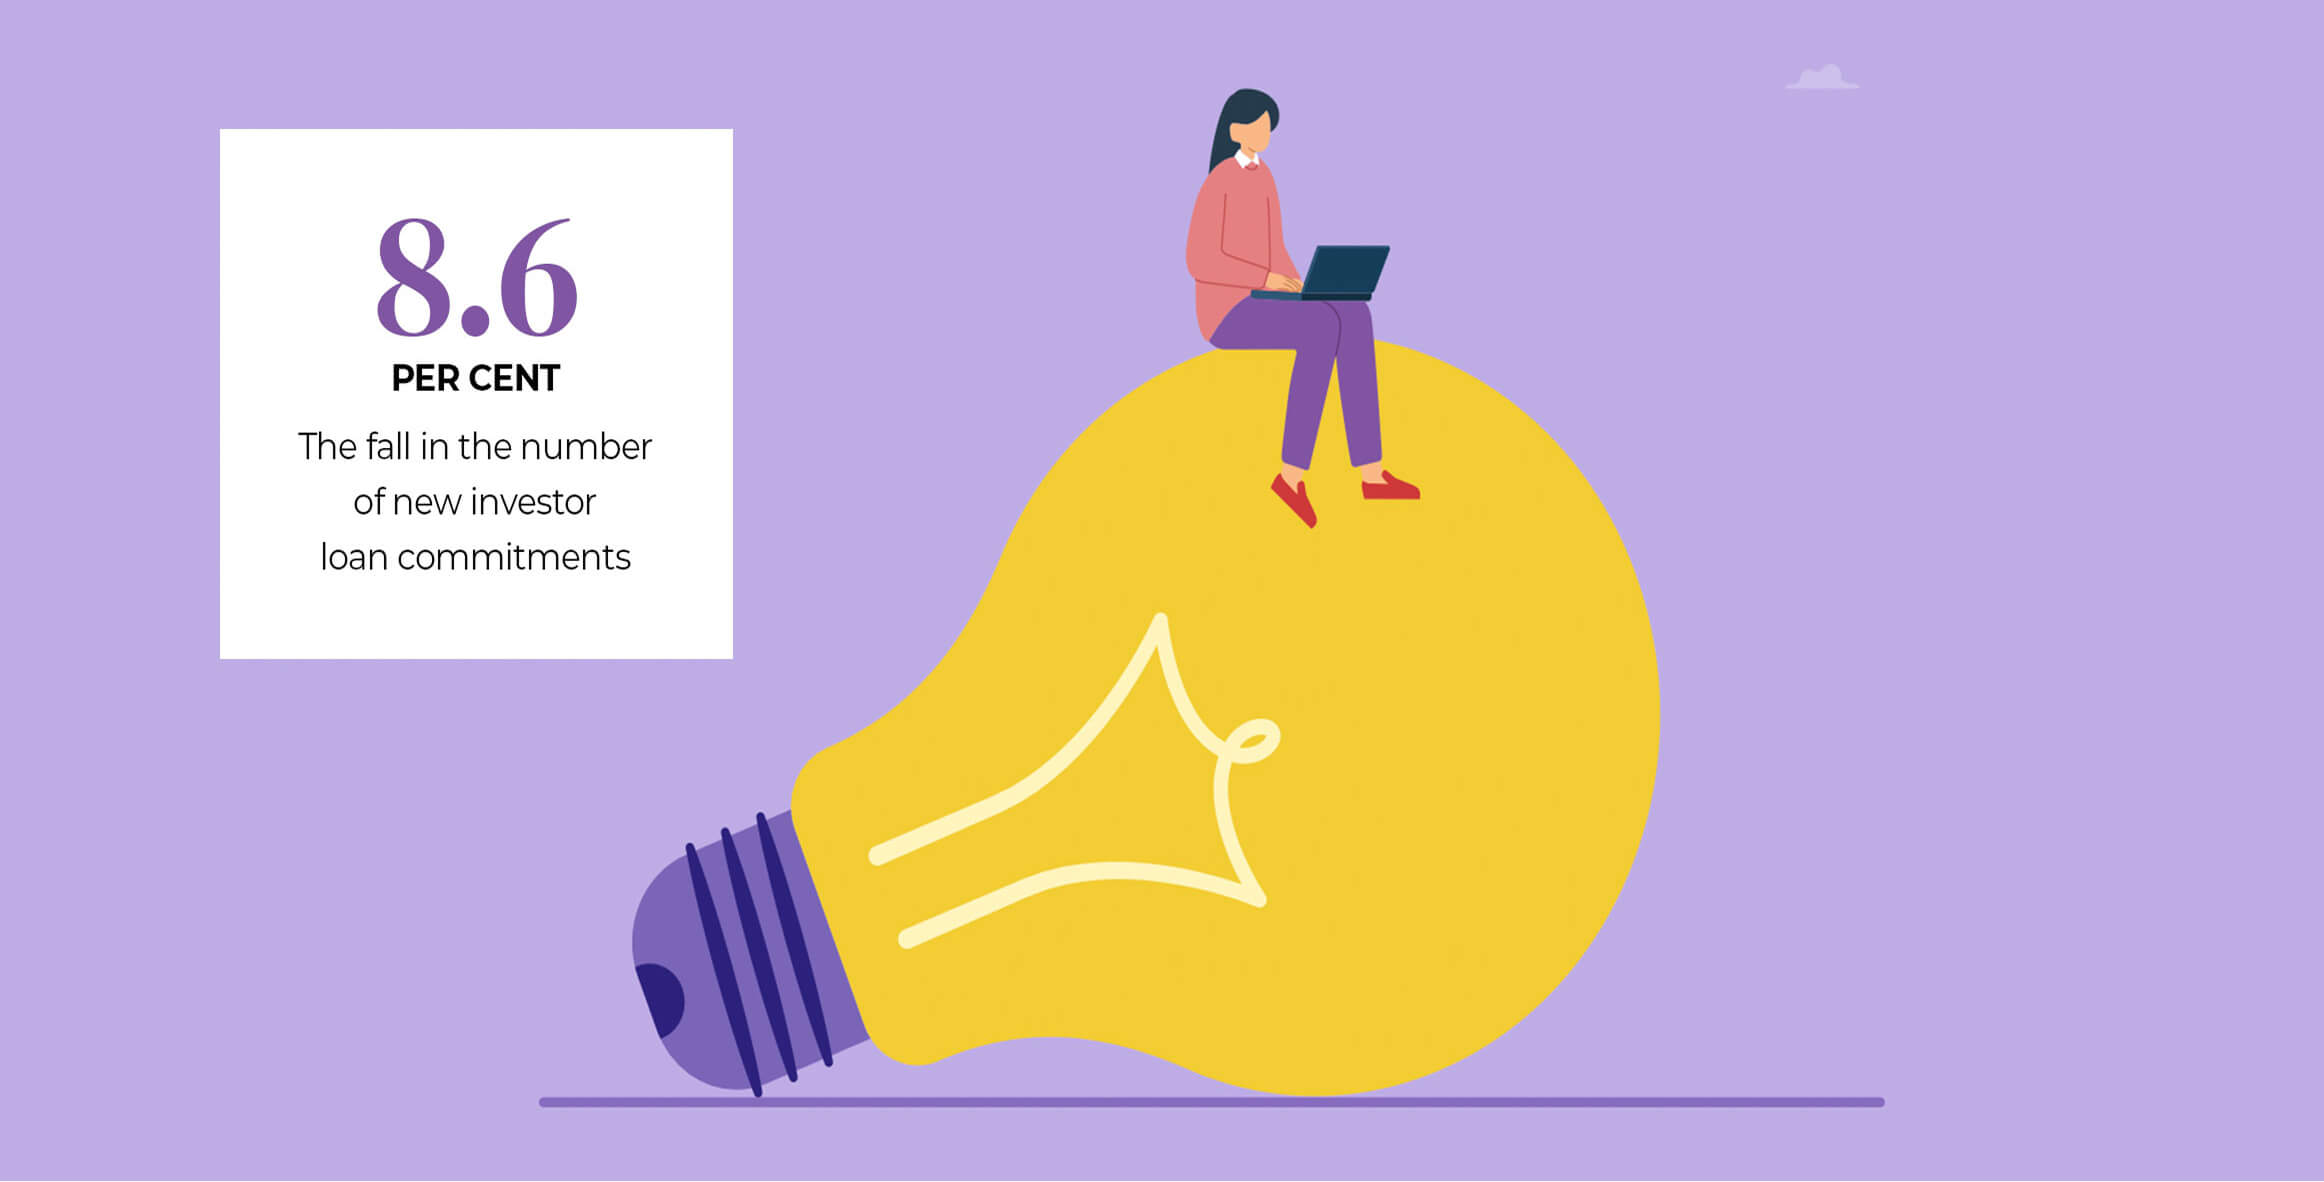
In the three months to 30 June 2026, the number of new investor loan commitments fell 8.6 per cent in seasonally adjusted terms, while the value of those commitments dropped 10.2 per cent.
This was well ahead of the declines recorded for new owner-occupier loans, with the number of commitments falling 3.3 per cent and their value declining 1.9 per cent.
This pullback has already filtered through to some of the major banks.
National Australia Bank (NAB) flagged a weaker mortgage pipeline during its third-quarter trading update in August, with investor applications declining 15 per cent.
The divergence was even more pronounced at Commonwealth Bank of Australia (CBA), where investor applications fell 28 per cent following the May federal budget, compared with a 9 per cent decline in owner-occupier applications.
While Australia and New Zealand Banking Group (ANZ) did not disclose investor flows in its latest trading update, the major noted overall mortgage applications fell 12 per cent.
Meanwhile, a similar trend was evident at Westpac, which reported a 26 per cent decline in investor applications during the June quarter.
Nathan Goonan, Westpac’s chief financial officer, attributed the weaker results to a combination of policy changes and higher interest rates.
“You’ve got a mortgage market that has got a period of real dislocation, whether it be through the budget changes, and then through rates,” Goonan said.
Goonan also noted the dip in investor demand had not been offset by first home buyers.
“We are seeing investor applications down more than owner-occupied. We haven’t necessarily seen first home buyers pick up the slack yet. But we would be cautious about drawing too many conclusions at this point in the cycle,” he said.
New approaches
Lenders wasted little time responding to the proposed tax reforms.
NAB and white label lender Connective Horizon were among the first to tell brokers that they were recalibrating their serviceability calculators. CBA also unveiled a new serviceability framework for investment lending, hard-coding the federal government’s proposed restriction of negative gearing to new builds.
One of the more notable moves came from non-major AMP Bank, which launched a product offering a 40-year loan term with an initial interest-only (IO) period of up to 10 years without requiring reassessment.
Designed for investment borrowers with a maximum loan-to-value ratio (LVR) of 80 per cent, the offering is available for loan sizes of $100,000 or more, with eligible customers able to lock in an IO period of between six and 10 years.
Speaking to The Adviser, Michael Christofides, AMP Bank’s director of lending and everyday banking, explained the thinking behind the new product.
“We have, of course, considered what’s been coming out from the budget, and cash flow pressures on investors have been building as a result of higher interest rates, which is a real pinch point for brokers and their clients as they look for solutions to enable their clients to get some certainty in the investment space,” he said.
“So we have been considering what our customers are saying and what our brokers are asking for, which is really that investors are looking for certainty, and they’re looking for cash flow, and this solution meets both of those needs.”
Cool heads prevail
The question now is whether the pullback in investor lending represents a temporary period of hesitation or the beginning of a broader shift in investor behaviour.
Speaking on The Adviser’s In Focus podcast, Julian Fadini, founder of Sydney-based property investment advisory firm PRPTY 360, urged investors to maintain a long-term perspective, saying that experienced investors may be looking beyond uncertainty for opportunities.
“I know that may sound counterproductive to the marketplace, but often what we’ve found is that investors that have been with us for the longest period of time are calling us now, looking to come back into the marketplace – as everybody’s out of the marketplace,” he said.
“Interest rate cycles don’t stay at the top of the cycle for extended periods of time. They may feel that way, but the reality is they don’t stay that way. What hasn’t changed is that the marketplace is, in terms of housing, severely undersupplied. While the sentiment’s not at its highest level, our more experienced investors, who’ve seen this before, are piling in.”
On another episode of In Focus, Bluestone Home Loans head of specialist lending Aaron Taylor said brokers have an important role to play in helping investors navigate the new landscape.
“Because If I’m a customer right now and I’m looking to buy an investment property, I go, ‘I don’t know what the right choice is.’ You walk into a bank and they’re going to give you one number that’s your borrowing capacity, but that’s the borrowing capacity at that bank,” he said.
Taylor also highlighted the challenges posed by constantly evolving reforms and policies, making effective co-ordination more important than ever.
“A month ago or two months ago, three months ago, this lender would have approved this loan. Now they’ve changed their policies and ‘I can’t go there anymore.’ And I think that’s where the brokers really need to keep up to speed with policy changes,” he said.
“The relationship with the BDM really comes into play. Making sure you’re in touch with the BDM and your key stakeholders. As things shift, we need to all be communicating with each other in the same way that the broker should be communicating with the financial planner and the accountant to make sure they understand what’s going on in their lives.
“Because there are a lot of changes in the planning space and in the accounting space as well. So, it’s about working together.”