Few business pressures are as immediate or as difficult to ignore as cash flow. Rising input costs, inflationary pressures, and elevated interest rates have all conspired to make this challenge more acute in 2026, compounding the difficulty of covering wages, taxes, bills, and those unexpected costs that inevitably crop up.
But keeping the lights on is just one side of the working capital conversation.
For many businesses, a lack of liquidity can be just as significant a constraint when demand is strong and growth opportunities are sitting on the table.
In this sense, the working capital question is sometimes less about ensuring the ongoing viability of a business and more about having enough cash available to purchase stock, take on larger contracts, hire additional staff, or accept more work.
Together, these two scenarios provide both clear opportunities for brokers.
As Accendo Financial founder Trent Carter explains on Finance Specialist, a podcast from The Adviser’s sister brand Broker Daily, the real success of a business sits on how much cash they have in the bank to do the things they want to do when they want to do it.
“Fundamentally, in its most basic sense, that’s what cash flow is – the ability to draw on your bank account to pay for wages, pay for rent, pay for your debt repayments, pay for the GST, pay for staff and your own wages as an owner,” he says.
“The stronger the cash flow, the more opportunity you’ve got to be able to do these things. Therefore, strong cash flow businesses have a bigger opportunity to grow unabated than a weak cash flow business.”
Feeling the squeeze
Data from non-bank lenders specialising in this space suggests a range of new factors are driving demand, with the recent introduction of Payday Super among the most notable. Commencing on 1 July 2026, the new regime requires employers to pay superannuation contributions into employees’ funds within seven business days of each pay run, rather than on a quarterly basis, and early signs suggest some businesses are feeling the pinch. For instance, the most recent SME Growth Index from lender ScotPac, released in September 2026, shows 74 per cent of SMEs were either not fully prepared for the change or expected it to negatively affect their cash flow.
Smaller businesses appear to be particularly exposed, with 83 per cent of SMEs turning over between $1 million and $5 million anticipating a negative cash flow impact, compared with 64 per cent of those generating between $5 million and $20 million.
The research also suggests that businesses are already looking at external funding to manage the transition, with 37 per cent planning to use some form of external facility rather than drawing on existing cash balances.
Commenting on the data, ScotPac CFO David Kirwan says the reform had effectively turned the payment of super into a “recurring working-capital event”.
“Payday Super doesn’t change the amount of super a business must pay, but it fundamentally changes when that money leaves the business,” Kirwan says.
“For SMEs operating with tight margins or uneven customer payment cycles, bringing forward those outflows can create a genuine liquidity squeeze.”
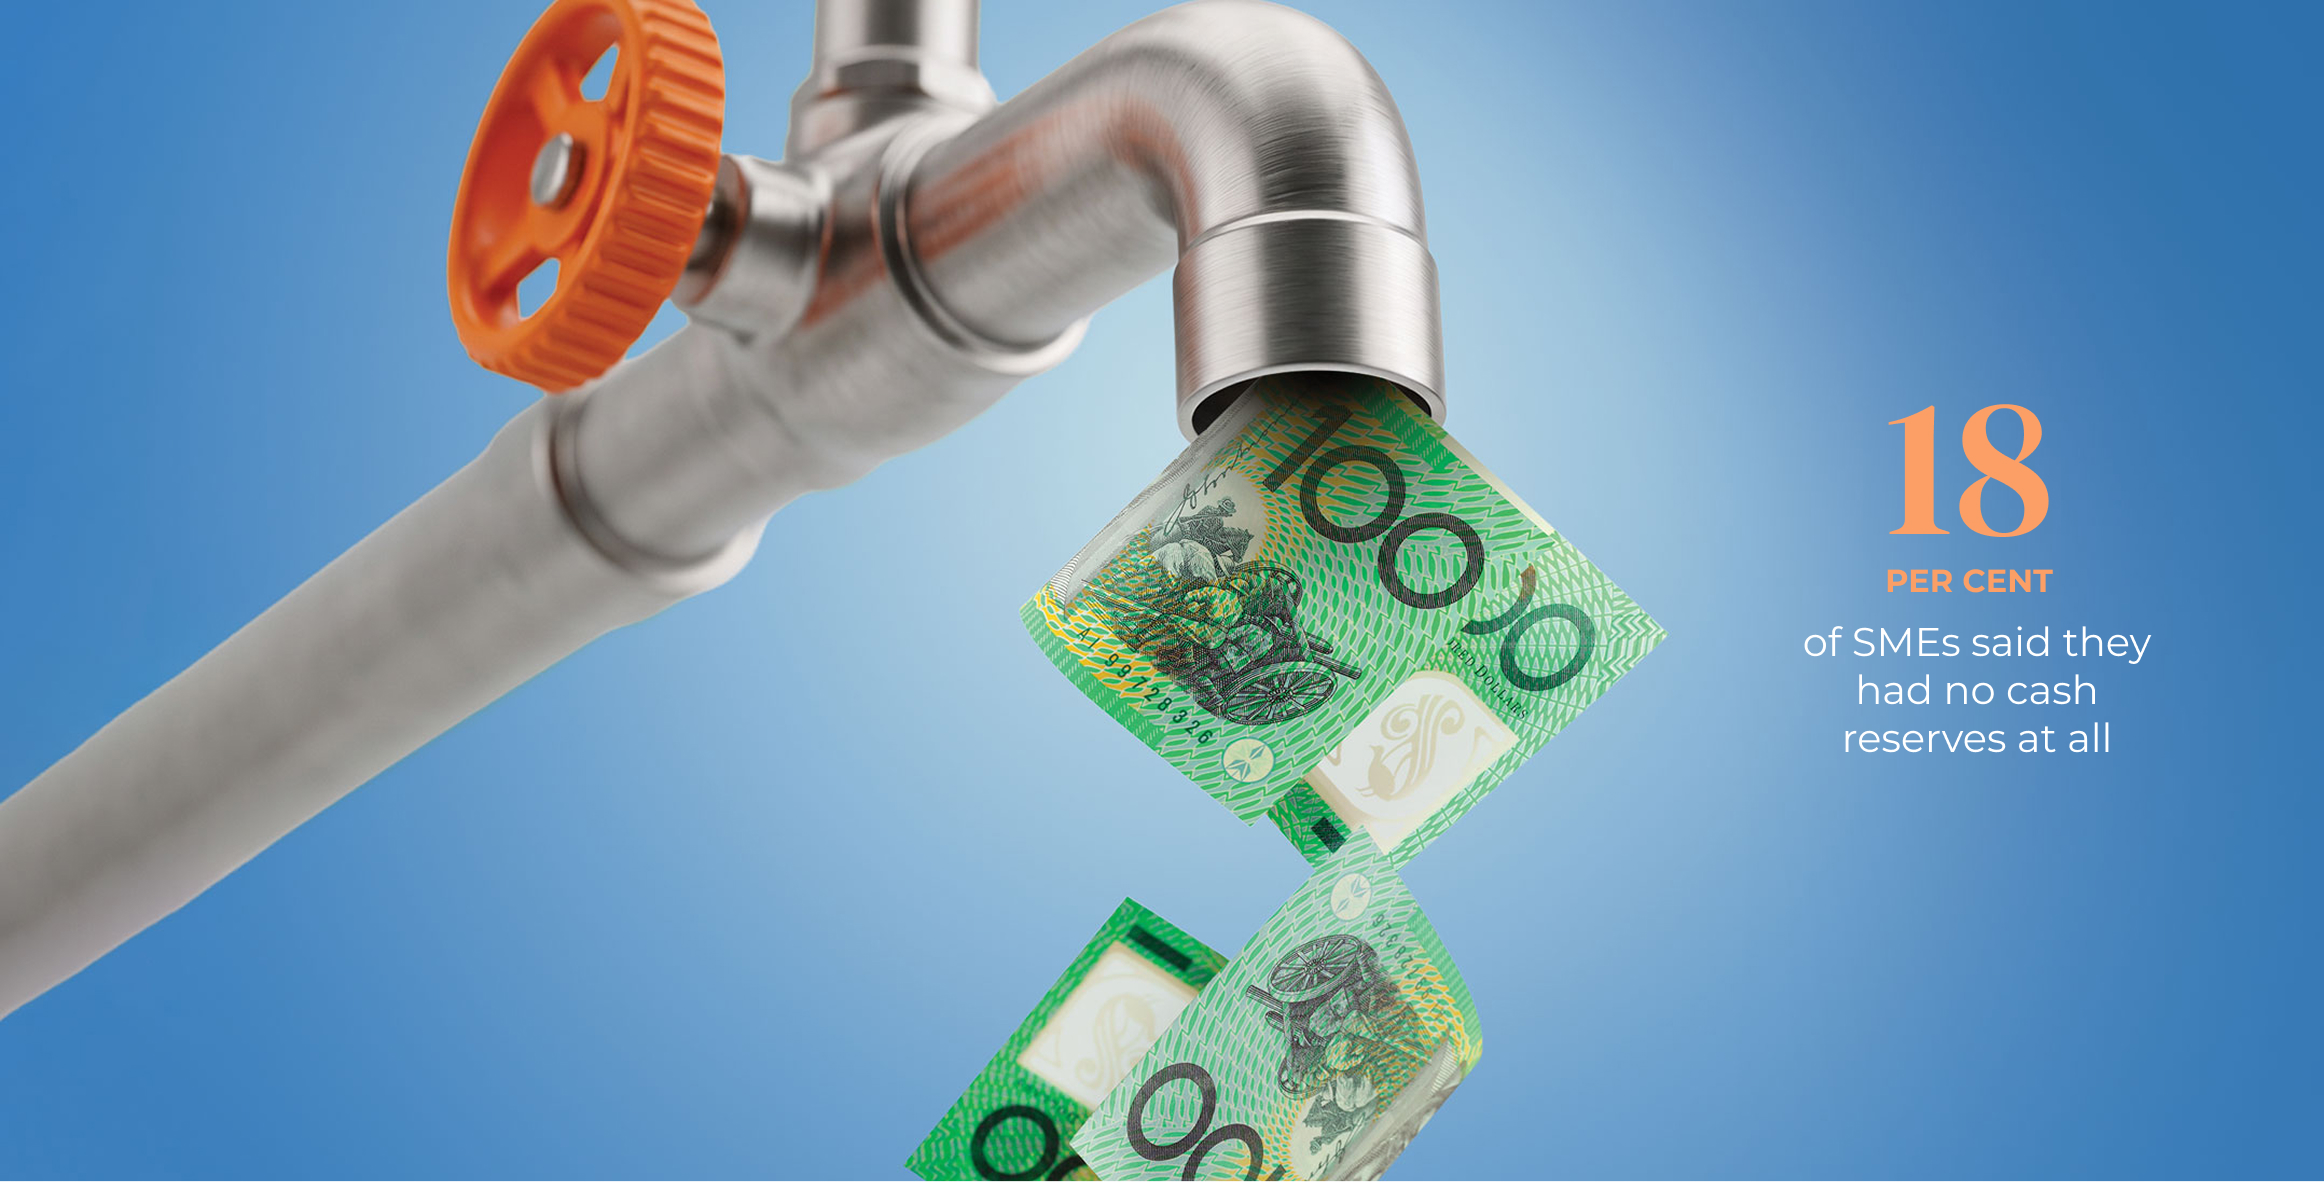
Elsewhere, data from Prospa suggests ongoing economic pressure has also translated into increased demand for cash flow solutions, with one in five (18 per cent) of respondents to the SME lender’s May 2026 SME Sentiment Report saying they had no cash reserves whatsoever.
For brokers, understanding the different pressures sitting behind a cash flow gap is becoming just as important as knowing where to find the funding to address it.
“Where a genuine timing gap exists, appropriately structured finance can help preserve liquidity and keep essential expenditure and investment on track,” Kirwan says.
“The right facility should match the business’s operating cycle and repayment capacity.”
The broker opportunity
Whether it’s buying materials required to take on a larger contract or simply keeping the shelves stocked, businesses need access to working capital in a range of scenarios.
So how can brokers help clients find the right solution?
Kellie Crocker from Queensland brokerage RLA Finance says rather than simply chasing the lowest rate, brokers should focus on structuring finance around the way cash moves through their clients’ businesses.
“Structure, security, flexibility and having someone you can actually call when things get complicated all matter,” she says.
Structure, security, flexibility and having someone you can actually call when things get complicated all matter”
- Kellie Crocker, RLA Finance
“A good broker can look at where the business has been, where it is now and where it’s going, then spread the risk across the right lenders. The right finance should make running the business easier – not create another problem six months down the track.”
And getting it right can deliver significant benefits, as Lumi NSW and ACT state manager Stephen Lew explained on a recent episode of The Adviser’s In Focus podcast.
“If you take the average home loan, say $735,000, the average commission is roughly 0.65 per cent. It’s about $4,800, plus a bit of a trail. But it’s a six- to 12-week process from application to settlement. And if the loan repays within a year, you’re looking at clawbacks,” he says.
“It’s a little bit different in our space. The typical working capital deal is around $150,000, so a fair bit smaller than the mortgage. But the upfront commissions can run up to 6.6 per cent. So, as much as $9,900. That’s just on the average deal. You get a lot of larger deals as well.
“And the good thing is those deals are funded in hours rather than months.”
Writing an opinion piece for The Adviser earlier this year, Tim Brown, CEO of mortgage group Recludo, said brokers would continue to play an important role in the cash flow side of commercial finance.
He said brokers are well placed to help clients identify and fill cash flow gaps, particularly as borrowers seek trusted advisers who can see the full picture.
“Banks will always play a central role in business lending, but the idea that they will continue to dominate the distribution of commercial finance without serious competition is becoming harder to defend,” he says.
“Because the reality is that mortgage brokers are already sitting in front of the clients, and once they start bringing those commercial opportunities to market at scale, the banks’ long-held grip on business lending will slip significantly.”